Levack restart puts Magna on two-mine track in Ontario
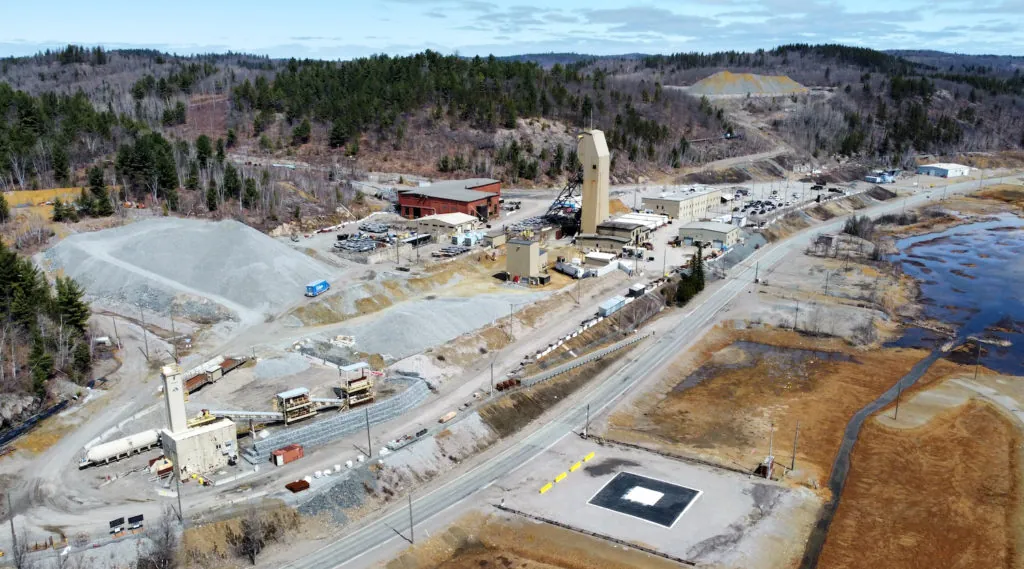
Levack is to join Magna’s producing McCreedy West mine as it builds a multi-mine business around Sudbury’s existing infrastructure.
Magna Mining (TSX: NICU; US-OTC: MGMNF) has approved a C$70-million ($49 million) restart of its Levack nickel-copper mine near Sudbury, Ont., targeting commercial production by mid-2028.
Thursday’s preliminary economic assessment values Levack, about 400 km north of Toronto, at $227 million after tax using a 7% discount rate.
That’s less than half Desjardins analyst Bryce Adams’ $497-million estimate at comparable metal prices, although he sees a stronger production plan for the mine’s contact nickel zones.
“The Contact Zone plan is stronger than we modelled, but the PEA excludes R2 which we view as strong future optionality,” Adams wrote in a Thursday note.
R2 is a copper and precious-metals discovery that hasn’t yet been included in a resource estimate.
Levack is to join Magna’s producing McCreedy West mine as the company builds a multi-mine business around Sudbury’s existing infrastructure.
Adams views the restart as a positive step despite the valuation gap.
The execution risk remains: Magna approved the investment without a feasibility study or mineral reserves demonstrating economic viability.
Magna’s Toronto-listed shares rose 0.4% to C$2.42 on Thursday afternoon, having touched C$1.88 and C$3.94 over the past 12 months.
The company has a market capitalization of about C$758 million ($532 million).
Initial capital of C$70.1 million exceeds Adams’ C$44-million forecast.
The estimate covers spending from January through June 2028 and includes C$12.6 million in contingency, according to the study.
Magna expects C$55.9 million in operating cash flow before commercial production and C$5.6 million in refundable tax credits to reduce its net cash outlay by the end of the ramp-up to C$8.6 million.
Those offsets don’t reduce the initial capital bill, and the credits remain subject to eligibility requirements.
The company ended June with C$40 million in cash and equivalents before Alpayana invested C$140 million for a 20% stake last month.
Magna can cover Levack’s initial capital from its balance sheet, Adams said.
The PEA forecasts a 92% after-tax internal rate of return.
Adams retained a speculative buy rating and C$5 share-price target.
Levack would produce an annual average of 12.9 million payable lb.
platinum, palladium and gold combined over 7.3 years, according to the study.
The plan calls for mining 5.75 million short tons at about 2,140 tons per day.
Operating costs average C$157.80 per ton processed, with another C$168 million in sustaining capital over the commercial production period.
Applying average September metal prices increases the after-tax net present value to $313.6 million.
Much of its infrastructure has been maintained because it provides secondary access for McCreedy West and nearby mines, Magna said.
Related News
- MiningIndia's 97 GW Coal Expansion Plan Looks Too Small, Senior Official Says
- MiningExplosives: The overlooked risk that could halt mines
- MiningOp-Ed: AI will not just add copper demand. It could change who sets the price
- MiningSouth America’s copper boom faces a $170B reality check
- MiningHertha Metals breaks ground on $100M US plant for magnet-grade iron
- MiningEnergyX inks 10-year, $2B lithium offtake deal with Trafigura