ADNOC Gas Is a Dividend Machine, But the Bill for “Growth” Is Arriving
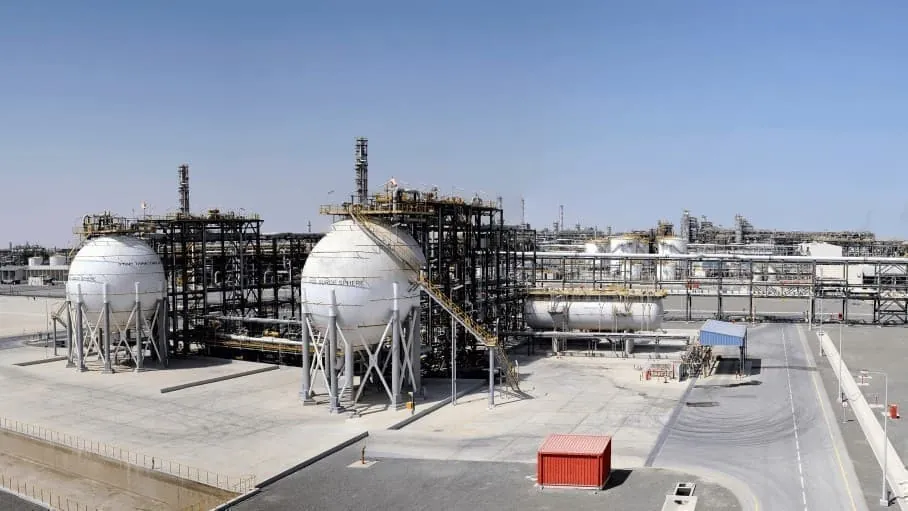
ADNOC Gas delivered a record 2025 net income of $5.2 billion despite falling revenues, underscoring a utility-like model.
The investment case is shifting as capex nearly doubled to $3.6 billion, ...
Home Oil Prices Oil Futures Rig Count Energy Energy-General Oil Prices Crude Oil Heating Oil Gas Prices Natural Gas Coal Company News Interviews Geopolitics Alternative Energy Nuclear Power Solar Energy Hydroelectric Renewable Energy Geothermal Energy Wind Power Fuel Cells Tidal Energy Biofuels Environment Global Warming Oil Spills Company News Breaking News Premium Articles My Account Get Exclusive Intel All Prices OPEC Blends Canadian Blends U.S.
Blends WTI Crude • 11 mins 95.63 +1.49 +1.58% Brent Crude • 11 mins 106.3 +0.63 +0.60% Murban Crude • 16 mins 110.6 -1.67 -1.49% Natural Gas • 11 mins 3.265 -0.018 -0.55% Heating Oil • 11 mins 4.918 -0.016 -0.32% Gasoline • 11 mins 3.255 +0.005 +0.14% Click Here for 150+ Global Oil Prices Gasoline • 11 mins 3.255 +0.005 +0.14% Heating Oil • 11 mins 4.918 -0.016 -0.32% WTI Midland • 6 hours 95.24 +0.42 +0.44% Opec Basket • 1 day 112.3 -1.73 -1.52% Indian Basket • 7 days 121.1 +3.47 +2.95% Click Here for 150+ Global Oil Prices Cyril Widdershoven is a senior maritime, energy, and geopolitical analyst and Senior Advisor at Blue Water Strategy, specialising in the strategic intersection of shipping, ports,… Abu Dhabi’s main gas company, ADNOC Gas, has presented its financials.
Again, the gas giant is being sold to investors as the perfect Gulf utility, based on its scale, stability, and domestic demand, and especially on its dividend stream, engineered to feel more like a sovereign coupon than an equity risk.
The numbers definitely support the story, as the company’s record full-year net income in 2025 is $5.2bn, which is an increase of 3% in comparison to FY2024.
These impressive figures are even more positive when you consider that its revenue fell 4% to $23.47bn.
These figures clearly illustrate how much of its profit engine is built on margin management and domestic contract structure, rather than on pure commodity price exposure.
Still, it should be already understood that “record earnings” could be playing a convenient cover for what really matters in 2026.
ADNOC Gas’s transition from a cash-harvesting phase to a capex-heavy industrial buildout will be critical, especially as it simultaneously promises shareholders a rising stream of distributions.
By 2025, ADNOC Gas saw its capex jump to $3.6bn, a 98% increase from the previous year.
It is not a rounding error; it is the point.
Analysts typically start to worry when capex doubles, as it signals that the investment case is no longer a simple yield story.
It is becoming an argument about execution risk and project discipline from the outset.
At the same time, it will be questioned whether the “national champion” is being run for minority shareholders or primarily linked to a national strategy.
Related News
- Oil & GasNew England natural gas prices have been trading near record discounts to Henry Hub
- Oil & GasWeekly average load in ERCOT continues near record high
- Oil & GasDangote Swings to $4.7 Billion Profit Ahead of Africa’s Biggest IPO
- Oil & GasWhy Diesel Prices Are So Much Higher Than Gasoline
- Oil & GasSaudi Arabia Becomes the Oil Market’s Biggest Wild Card
- Oil & GasTrump Defends Russian Diesel Deal as Energy Ceasefire Claims Unravel